Philadelphia Metro — At a Glance
Curious what this means for your street, or thinking about your next move?
Schedule a CallFall Market Update: National Trends, Philadelphia Metro, and What It Means in Springfield Township, Mount Airy, and Chestnut Hill – September 2026
Before getting into the numbers: the data through August points to a market that’s finally giving buyers a little more room to breathe, right as we head into a season that historically favors them anyway. Here’s what’s happening nationally, across the Philadelphia region, and in the specific neighborhoods where the Larry DiFranco Team works most.
National housing market
Fall has historically been a better time for buyers to shop. Homes that didn’t sell over the summer are still on the market with less competition, inventory tends to peak this time of year, and list prices typically start easing. Sellers who cut prices do so more often in fall than any other season — historically close to 17% of listings see a price cut in the September-through-November window, compared with roughly 12–13% in spring.
There’s also a broader divide worth knowing about depending on your price point. Luxury home sales are up more than 6% year-over-year while starter-home sales have fallen more than 5%, and starter-home inventory is growing faster than luxury inventory. Selling at the entry-level price point means more competition from other sellers; selling — or buying — at the upper end, demand is still working in your favor.
Philadelphia metro area
Closer to home, the Philadelphia metro area is showing the same late-summer cooling that tends to show up this time of year. Closed sales in August were down 3% year-over-year and roughly 10% from July, though some of that is normal seasonal slowdown. New listings and active inventory are both up meaningfully from a year ago — active listings are up over 14% — even though showings have actually been down for three months running.
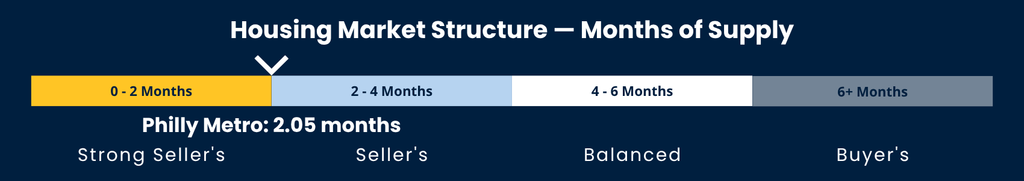
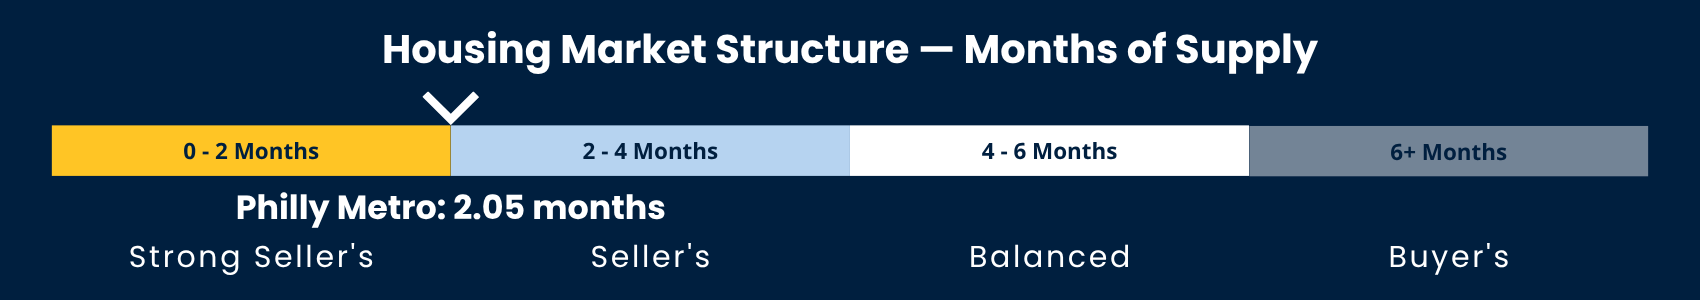
The number that stands out is price: the median sold price rose almost 5% year-over-year to $425,000, driven in part by a bigger share of higher-end sales closing this month. Months of supply crept up to 2.6, still firmly favoring sellers, but a bit less tight than it’s been. With mortgage rates still above 6.5%, expect price growth to slow and buyers to gain a little more leverage moving into fall.
Springfield Township
Inventory ticked up from July into August, and months of supply moved from under one month to 1.4 — still a tight, seller-favoring market, but with more breathing room than earlier in the summer.
Momentum told a mixed story: new listings picked up while pending sales slowed slightly and closings held roughly steady. The bigger shift was on the pricing side — days on market more than doubled month over month, and it’s now well above where it stood a year ago. That’s less a sign that demand disappeared and more a sign that buyers are being more selective. The homes priced and presented well are still moving; the ones priced aspirationally are sitting longer than they would have a few months ago.
Mount Airy
Mount Airy actually tightened up a bit this month. Inventory came down from July, and months of supply eased from 3.6 to 2.8 — still the most balanced of the three markets we track, but moving toward sellers rather than away from them.
Days on market improved noticeably from July, though it’s still well above where it was a year ago, and the median sold price jumped to $565,000 from $426,000 in July. A swing like that usually reflects which homes happened to close that month more than a sudden shift in values — in this case, likely more activity at the higher end, echoing the national luxury-versus-starter divide. Worth watching over the next month or two rather than reading too much into a single data point.
Chestnut Hill
Chestnut Hill is a small, high-price market, so the numbers move around more than the others — that’s normal, not a red flag. Inventory eased from July, months of supply dropped from 4.0 to just over 2, and days on market ticked up slightly but remains fast by any standard.
The sold median swung sharply, from just under $1.19 million in July to $700,000 in August — again a function of which specific homes sold rather than a market shift. In a market this size, pricing and positioning still matter enormously, because the buyer pool for any given listing is small and highly informed.
Where this leaves us
Supply is easing nationally and regionally, right as the season that traditionally favors buyers gets underway — but locally, none of these three markets have moved anywhere close to buyer’s-market territory. Springfield and Chestnut Hill remain tight by any standard, and even Mount Airy, the most balanced of the three, tightened rather than loosened this month.
For sellers, that means preparation and realistic pricing matter more than they did earlier in the year. For buyers, fall’s traditional advantages are showing up in the national data, even if local inventory hasn’t fully caught up yet.
If you want to talk through what any of this means for your street or your specific plans, reach out.