Philadelphia Real Estate Market Update — October 2026
Fall settled over Eastern Montgomery County and Northwest Philadelphia with a market still being shaped by one thing: mortgage rates stuck in the high-6% to mid-7% range. Closings slowed again both nationally and across the Philadelphia metro in September, but underneath that headline, Springfield Township, Mount Airy, and Chestnut Hill each told a different story. Here’s what the September 2026 numbers show, and what they mean if you’re buying or selling this fall.
The National Picture: Rates Are Still the Story
The Federal Reserve raised rates again this fall to keep pressure on inflation, and forecasters don’t expect meaningful relief on the 30-year mortgage rate before 2027 — most now put a floor somewhere in the mid-6% range, with plenty of panelists expecting rates to hold in the high-6s to 7%-plus well into next year.
One way to make sense of today’s market: there isn’t really one housing market right now, there are four. Cash buyers — still roughly a quarter to a third of sales nationally — are living in a different world than everyone else, moving fast with no financing contingency. Buyers who need financing are increasingly being met with concessions, as nearly half of sellers nationally now offer a rate buydown or credit rather than cutting price outright. Homeowners locked into 3% rates are largely staying put rather than trading up into something higher. And builders, sitting on the most new-home supply in years, are leaning hard on incentives to move inventory.
For buyers, that means getting pre-approved so you know your real budget, comparing more than one lender’s quotes, and asking about concessions or a rate buydown instead of waiting for rates to drop. For sellers, it means pricing for today’s buyer, making sure the home is move-in ready, and building a concession into your strategy up front rather than treating it as a last resort.
Philadelphia Metro: A Market Taking a Breath
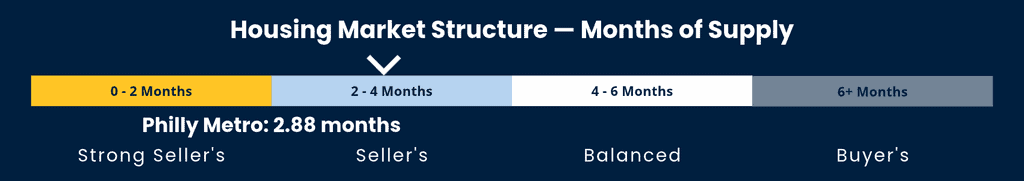
Inventory kept building across the metro in September. Active listings were up 19.6% year-over-year to 15,528, and new listings — up just 0.7% year-over-year — jumped 11.3% from August alone. Months of supply rose to 2.88, still within seller’s-market territory by historical standards, but loosening steadily month over month.
Buyer activity pulled back to match. Closed sales fell 2.9% year-over-year to 5,247 — the second straight month of year-over-year declines — while new pending contracts dropped 10.7% to 5,159, the lowest September total since 2013. Showings were down 10.5% as well, a clear sign that higher rates, not a lack of interest, are what’s holding activity back.
Pricing held up better than activity did. The metro’s median sold price was $400,000 in September, up 2.6% year-over-year, though down from August’s $425,000 as the usual seasonal cooling set in. Median days on market held flat year-over-year at 16 days. Montgomery County continued to outperform the broader metro, with closed sales up 3.7% year-over-year and median price up 8.1% to $469,000. As Bright MLS put it, hopes for a strong fall market have largely been dashed by rates in the mid-7% range, with 2026 sales expected to track below 2025 through the rest of the season.
Springfield Township
Inventory: Springfield stayed tight. Months of supply sat at just 1.6 — squarely in strong seller’s territory — with end-of-month inventory at 30 homes, essentially flat with August’s 27 and well below last September’s 33.
Momentum: New listings held at 22, unchanged from August but down sharply from 37 a year ago — far fewer sellers tested the market this September than last. Thirteen homes went under contract, identical to August and down from 16 a year ago, while 15 closed, up from August’s pace but still well above last September’s 11.
Pricing: The median sold price jumped to $640,000, up from $500,000 in August and $460,000 a year ago — worth reading with some caution, since that reflects a smaller September sample skewed toward higher-value sales rather than a one-month surge in values. More telling is days on market, which stretched to 48, up from 27 in August and just 12 a year ago. Even with inventory this thin, buyers are taking their time. For sellers, that means presentation and pricing still matter — low supply alone won’t move a home quickly. For buyers, it means less competition for what’s listed, with the trade-off of a thinner selection to choose from.
Mount Airy (19119)
Inventory: Months of supply rose to 3.4, up from 2.8 in August and roughly flat with last September’s 3.3 — comfortably in balanced-to-seller’s territory, with end-of-month inventory at 79 homes, the deepest of the three markets we track.
Momentum: New listings climbed to 36, up 16% from August and nearly matching last September’s 37 — sellers remain active here. Seventeen homes went under contract, flat with August and up from 15 a year ago, while 24 closed, roughly in line with both August and last September.
Pricing: The median sold price was $450,000, up a modest 1.4% year-over-year but down notably from August’s $565,000 — a pullback that lines up with the seasonal cooling seen across the metro rather than a shift in underlying value. Days on market rose to 36, up from 25 a year ago but down from August’s 40. For sellers, Mount Airy’s steady new-listing and pending activity shows buyers are still engaged — correct pricing from day one continues to get results. For buyers, there’s a bit more breathing room than a few months ago as inventory builds.
Chestnut Hill (19118)
Inventory: Months of supply rose to 3.3, up sharply from August’s 2.1 and roughly flat with last September’s 3.1, as the market moves toward more balance after a tight summer. End-of-month inventory reached 30 homes, up from 25 in both August and a year ago.
Momentum: New listings surged to 18 in September, compared with just 4 in August and 13 a year ago. More telling: 12 homes went under contract — six times August’s count of 4 and last September’s count of 2 — a sharp pickup in buyer commitment, even though only 6 homes actually closed, down from 9 in August and 8 last September, since September closings reflect contracts written during the quieter summer weeks.
Pricing: The median sold price reached $799,500, up 10.8% year-over-year and 14.2% from August — Chestnut Hill’s upper tier continues to command premium pricing even in a higher-rate environment. Days on market rose to 31, more than double last September’s 14, though buyers at this price point typically take longer to decide. For sellers, the jump in pending contracts is the number to watch — it points toward stronger closings this winter. For buyers, well-priced listings are drawing real interest again, so be ready to move when the right one appears.
What It All Means This Fall
Three related but distinct stories this September: Springfield Township’s tight inventory keeps favoring sellers even as buyers slow down to make sure a home is right. Mount Airy is settling into a steady seasonal rhythm with healthy activity on both sides. And Chestnut Hill’s jump in pending contracts suggests the quieter summer months are giving way to real momentum heading into the final quarter of the year. The thread running through every market we track for Eastern Montgomery County and beyond is pricing discipline — it’s what’s working right now, for buyers negotiating in a higher-rate environment and for sellers who want to avoid sitting on the market. If you’re weighing a move this fall, or just want to know what your home is worth in today’s market, use the buttons above to grab time on our calendar or request a full market report for your neighborhood.